Chime – Mobile Banking
ChimeFinanceVerified
- 229.63K Reviews
- 4.8
- Downloads
- 10,000,000+
- Price
- Free
Screenshots
 Analysis by Appwesome
What makes mobile banking useful to me is not a pile of features; it’s whether the app helps me handle the awkward gaps between bills and payday without adding another chore. That is the lens I use for Chime – Mobile Banking. Its most practical appeal is a combination of early access to direct deposits and a fee-free overdraft option. Those can matter when a payment is due before the next paycheck, though neither turns a tight budget into a comfortable one.
Why earlier access can change a payday routine
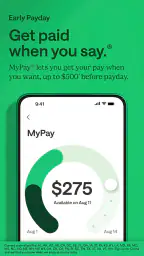
When a paycheck arrives, the timing can shape the whole week: rent, groceries, and automatic payments do not always line up neatly. Chime’s early direct deposit is intended to make qualifying pay available before the usual payday. In everyday use, that can offer more room to plan, rather than waiting until the standard deposit date to move money around.
I would treat the earlier timing as a useful possibility, not a guaranteed calendar promise. A deposit still depends on the employer or benefits payer sending the payment information, so I would not schedule a bill around an assumed early arrival until I had seen how my own deposits behave. The safer habit is to budget around the regular payday and regard an earlier arrival as breathing room.
Making the feature work for a real budget
Imagine your paycheck normally arrives near the end of the week, but groceries and a utility payment fall due beforehand. If the deposit becomes available early, you may be able to cover those essentials without shifting money from another account or relying on a credit card. The useful part is not just having the balance sooner; it is being able to check the account and decide what must be paid now and what can wait.
I’d use that flexibility to set a simple order: cover fixed necessities first, leave a cushion for pending spending, and only then decide what is safe to save or spend. That last step matters because an early deposit can feel like extra money even though it is still the same paycheck. Treating it as a timing change, rather than a raise, keeps the benefit from quietly encouraging overspending.
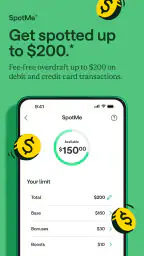
The fee-free overdraft option can be another buffer for an unexpected shortfall. I see that as a backup for a genuine mismatch between a purchase and incoming money, not as a routine way to stretch every pay period. Before relying on it, I’d read the in-app terms and check the eligibility and limits that apply to my account. An overdraft cushion can soften a bad moment, but it does not replace tracking the balance.
Where Chime fits among banking choices
Compared with a traditional bank app, Chime is appealing if what you want is a straightforward phone-based way to manage everyday banking without monthly fees. A local bank may be a better fit if you depend on in-person help or want to keep a long-standing relationship with a nearby branch. A credit union can also suit someone who values local service and is comfortable with its particular account options.
Other Stories to Read




Compared with a budgeting app, Chime is not simply a place to view accounts held elsewhere: it is a banking app centered on managing money through its own service. A separate budgeting tool may offer a broader view if you use several banks, cards, or cash accounts. I would choose based on the job I need done: convenient access to everyday banking, or a consolidated picture across multiple providers.
Small habits that make the experience more useful
One practical approach is to check the account around payday and review upcoming payments before treating the deposit as available spending money. That quick pause helps catch subscriptions or bills that might otherwise surprise you. If you use automatic savings, think about whether the amount being moved still leaves enough for near-term expenses; a saving habit is only helpful if it does not create a cash squeeze a few days later.
Round-ups can make saving feel less like a separate task because small amounts accumulate as you spend. I would not count on round-ups to build an emergency fund quickly, though. They are better viewed as a low-effort supplement to a deliberate savings plan. If you are saving for a specific bill, setting aside a planned amount is more predictable than relying only on spare change from purchases.
Spending insights are most useful when you act on them. I’d scan the categories for a pattern—such as frequent food purchases or recurring charges—and then decide whether it reflects a choice I’m happy with. A chart cannot tell you what to cut, and a category total can be misleading if transactions are grouped differently than you expect. The benefit is having a prompt to look closer, not an automatic diagnosis of your finances.
What to consider before switching
A banking app can make daily tasks easier, but moving your main account is still a practical project. I would first list every place that sends or takes money from the old account: payroll, rent, utilities, subscriptions, and any person who regularly pays me back. Updating them in a deliberate order reduces the chance that an old payment instruction causes a missed deposit or a returned bill.
I would also keep a transition cushion in the previous account until pending transactions have cleared and the new deposit routine is familiar. That is not a special Chime feature; it is a sensible precaution whenever changing where everyday money flows. People who need frequent cash handling, branch visits, or a particular service from their current bank should compare those needs before moving their primary banking over.
Chime is a finance app from Chime, and its appeal is clearest for people who want mobile access, a simpler fee structure, and the possibility of getting direct deposits sooner. It is free to download, rated for Everyone, and has a 4.8 average from around 977,000 ratings, with over 10 million installs. Those figures show broad interest, but they do not tell me whether it matches an individual’s banking needs.
The main trade-off is that convenience can encourage people to rely too heavily on timing features or a short-term overdraft cushion. I’d still keep a small balance buffer where possible and check the terms inside the app before depending on any account benefit. If your priority is in-person service or a full overview of accounts at several institutions, another option may be a better fit.
For someone comfortable handling money on a phone, especially someone trying to manage the days around payday, Chime is worth considering. Its current version is 5.310.1, and the most useful question is not whether early access sounds appealing in general, but whether the timing and everyday banking tools suit your own income and bill schedule. I’d start by using it for a clear routine, then decide whether it deserves to become the account I rely on most.
Easy Setup and No Hidden Fees
First things first, getting started with Chime is a piece of cake. I mean, who doesn’t love an app that doesn’t make you jump through hoops just to sign up? With no credit checks and no hidden fees, Chime sets a pretty chill tone from the get-go. It’s like they’re saying, “Hey, we got you.”
One of the coolest features is the early direct deposit. If you're someone who likes having access to your money a couple of days early, this can be a real game changer. Imagine getting paid on Wednesday instead of Friday. It’s like a little mid-week treat!
Automated Savings and Spending Insights
Now, let’s talk saving. Chime does this nifty thing where it automatically rounds up your transactions to the nearest dollar and stashes the difference in your savings account. I found this super helpful because, let’s be honest, saving can be tough. Every little bit counts, right?
And if you’re trying to keep tabs on your spending, Chime’s got your back. The app provides spending insights that show you exactly where your money is going. It’s like having a personal financial advisor whispering in your ear.
Security and Customer Support
In the world of mobile banking, security is a biggie, and Chime doesn’t disappoint. They use industry-standard encryption, which is a fancy way of saying your money and data are safe. Plus, if you ever lose your card, you can instantly disable it in the app. No more panic attacks!
Customer support is available through the app, and they’re pretty responsive. I had a couple of questions while setting things up, and their team was quick to help out. It’s always reassuring to know there’s a real person ready to assist when you need it.
Features That Stand Out
Apart from the basics, Chime offers some cool features like the ability to pay friends directly through the app. It’s super handy for splitting bills or paying someone back. The interface is clean and intuitive, so you won’t find yourself lost in a maze of buttons and menus.
Also, there are no overdraft fees, which is a huge relief for those unexpected moments when you might go a little over your balance. It’s like having a safety net without the extra cost.
Overall, Chime – Mobile Banking is designed for the modern user who values simplicity, transparency, and efficiency. If you’re looking for a way to manage your finances effortlessly, this app might just be your new best friend.
So, if you’re tired of traditional banking woes and want something that fits right into your pocket, give Chime a try. It’s a fresh take on banking that might just change the way you handle your money.
Highlights
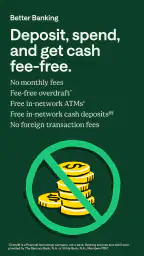
- No monthly fees or overdraft charges.
- Early direct deposit access.
- User-friendly interface.
- Automatic savings features.
- Wide network of ATMs.
Limitations
- Limited cash deposit options.
- No physical branches.
- ATM fees outside network.
- Mobile check deposit limits.
- No joint accounts available.
Frequently Asked Questions
01What features does Chime – Mobile Banking offer?
Chime – Mobile Banking provides a range of features designed to simplify personal finance management. Users can enjoy fee-free overdrafts, automatic savings, direct deposit access up to two days early, and real-time transaction alerts. Additionally, Chime offers a user-friendly interface with mobile check deposit and a Visa debit card for everyday transactions.
02Is Chime – Mobile Banking secure to use?
Yes, Chime – Mobile Banking emphasizes security by using advanced encryption and biometric authentication such as fingerprint and facial recognition. The app is insured by the FDIC up to $250,000 through its banking partners, ensuring your money is safe. Chime also provides instant transaction alerts to help monitor account activity.
03Are there any fees associated with using Chime?
Chime – Mobile Banking is known for its no-fee structure. Users enjoy fee-free overdrafts, no monthly maintenance fees, no minimum balance requirements, and no foreign transaction fees. However, there may be fees for using out-of-network ATMs or certain expedited services, so it's advisable to review their fee schedule closely.
04How can I deposit and withdraw money with Chime?
Depositing and withdrawing money with Chime is simple. You can deposit funds via direct deposit, mobile check deposit, or by transferring from external bank accounts. Withdrawals can be made at over 60,000 fee-free ATMs nationwide, or you can use the Chime Visa debit card for purchases and cash back at participating retailers.
05What customer support options are available with Chime?
Chime offers robust customer support through various channels. Users can contact support via the in-app chat, email, or phone for assistance with their accounts. The Chime app also includes a comprehensive help center with FAQs and troubleshooting guides to address common user inquiries efficiently.


